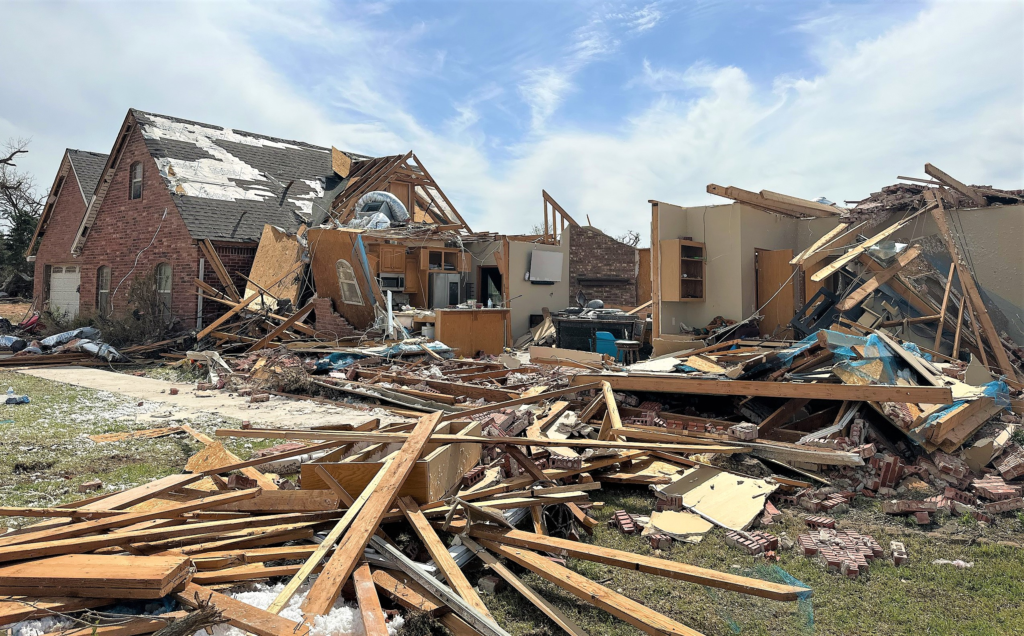
The aftermath of an Oklahoma tornado. (National Oceanic and Atmospheric Administration photo via Wikipedia Commons)
When major disasters strike, the IRS usually provides affected taxpayers tax relief. That generally includes new, later deadlines. In some cases, that means tax returns that are on extension are extended even longer.
.
The Oct. 15 extended filing deadline for 2025 tax year returns is almost here. But some people won’t have to meet the due date.
The Internal Revenue Service has given them more time to file their extended return.
Unfortunately for them, the reason is because they live or own a business in an area that was declared a major disaster area.
These extended extension deadlines apply to taxpayers in those areas who had a valid extension to file their 2025 individual income tax returns.
And again, as noted in my October Tax Moves post, this extended extension time generally is for filing 1040 forms only. Tax owed in connection with the extended 2025 returns was due on April 15.
So, even those the disaster-affected filers have more time to finish their forms, late-payment penalty and interest charges will continue to accrue on their unpaid taxes until the IRS gets the money.
Wide range of disasters, deadlines
.
10 states and beyond covered: The taxpayers with extensions are in 10 states and the Freely Associated State of the Commonwealth of Northern Mariana Islands (CNMI).
Links to the IRS disaster tax deadline changes for the affected areas are listed below.
Taxpayers in five states now having an early November due date. Those in 13 areas given until next February to file.
The ongoing conflict in the Middle East also prompted the IRS to provide additional tax relief and a September 2027 deadline for a wide range of U.S. tax obligations to affected individuals and businesses.
Links to the IRS announcements of the relief and new deadlines are listed below by the extension dates. Because an angry Mother Nature roams, Mississippi taxpayers with even longer deadlines fall into two dates, as do CNMI filers, who were doubly pummeled by huge Pacific typhoons.
Nov. 2, 2026, disaster deadline:
- Louisiana: LA- 2026-02, IRS announces tax relief for taxpayers and businesses in Louisiana affected by Tropical Storm Arthur that began on June 17, 2026
- Michigan: MI-2026-02, IRS announces tax relief for taxpayers impacted by severe storms, tornadoes and flooding in the State of Michigan, various deadlines postponed to Nov. 2, 2026
- Mississippi: MS-2026-02, IRS announces tax relief for taxpayers impacted by severe storms, straight-line winds, tornadoes and flooding in the State of Mississippi, various deadlines postponed to Nov. 2, 2026
- Wisconsin: WI-2026-02, IRS announces tax relief for taxpayers impacted by severe storms, tornadoes and flooding in the State of Wisconsin, various deadlines postponed to Nov. 2, 2026
- Northern Mariana Islands: NMI-2026-01, IRS announces tax relief for taxpayers impacted by Super Typhoon Sinlaku in the Commonwealth of the Northern Mariana Islands; various deadlines postponed to Nov. 2, 2026
.
Feb. 1, 2027, disaster deadline:
- Hawaii: HI-2026-03, IRS announces tax relief for taxpayers impacted by the earthquake in Hawaii County; various deadlines postponed to Feb. 1, 2027
- Indiana: IN-2026-01, IRS announces tax relief for taxpayers impacted by severe storms, straight-line winds, tornadoes, and flooding in Indiana, various deadlines postponed to Feb. 1, 2027
- Nebraska:
- NE-2026-03, IRS announces tax relief for taxpayers impacted by March wildfires in Nebraska, various deadlines postponed to Feb. 1, 2027
- NE-2026-04, IRS announces tax relief for taxpayers impacted by April wildfires in central Nebraska, various deadlines postponed to Feb. 1, 2027
- NE-2026-05, IRS announces tax relief for taxpayers impacted by severe storms in Nebraska, various deadlines postponed to Feb. 1, 2027
- NE-2026-06, IRS announces tax relief for taxpayers impacted by May wildfires in Nebraska, various deadlines postponed to Feb. 1, 2027
- NE-2026-07, IRS announces tax relief for taxpayers impacted by June wildfires in Nebraska, various deadlines postponed to Feb. 1, 2027
- Mississippi: MS-2026-03, IRS announces tax relief for taxpayers impacted by Tropical Storm Arthur in Mississippi, various deadlines postponed to Feb. 1, 2027
- South Dakota: SD-2026-05, IRS announces tax relief for taxpayers impacted by severe storms, straight-line winds, and flooding in the Oglala Sioux Tribe, various deadlines postponed to Feb. 1, 2027
- Washington:
- West Virginia: WV-2026-01, IRS announces tax relief for taxpayers impacted by severe storms, straight-line winds, tornadoes, flooding, landslides and mudslides in West Virginia, various deadlines postponed to Feb. 1, 2027
- Northern Mariana Islands: NMI-2026-02, IRS announces tax relief for taxpayers impacted by Super Typhoon Bavi in the Northern Mariana Islands, various deadlines postponed to Feb. 1, 2027
.
Sept. 30,2027, special international deadline: The IRS on Sept. 30 announced additional tax relief to affected individuals and businesses in Israel, the West Bank, and Gaza who must meet U.S. tax requirements. This includes filing federal returns, making tax payments, and performing other time-sensitive tax-related actions.
The affected tax filing and payment deadlines are those that occurred or will occur during the period from Sept. 30, 2026, through Sept. 30, 2027. Affected taxpayers now have until the end of that period, specifically Sept. 30, 2027, to meet these various tax obligations, per IRS Notice 2026-63.
The latest IRS guidance follows up on prior guidance. That is —
- Notice 2023-71, which originally provided relief to taxpayers affected by the Oct. 7, 2023, attacks in Israel;
- Notice 2024-72, which provided relief to taxpayers affected by terroristic action in Israel throughout 2023 and 2024; and
- Notice 2025-53, which provided relief for taxpayers affected by terroristic action in the State of Israel throughout 2024 and 2025 by providing relief until Sept. 30, 2026.
All these IRS notices provide separate but overlapping relief to taxpayers who, due the terroristic action in Israel, may be unable to meet a tax-filing or tax-payment obligation, or may be unable to perform other time-sensitive tax-related actions.
The assorted directives essentially postpone a variety of tax filing and payment deadlines that occurred or will occur during the period from Oct. 7, 2023, through Sept. 30, 2027.
Other IRS relief in disaster situations
.
Automatic disaster and special relief: In all cases, the IRS notes that it automatically identifies taxpayers whose principal residence or principal place of business is located in covered areas and applies the relief.
The IRS does this based on the taxpayers’ previously filed returns. This is another reason to let the IRS know when you move.
Other eligible taxpayers, or their representatives, whose filing address is outside the covered area can obtain relief by calling the IRS disaster hotline toll free at (866) 562-5227 and identify the date they qualified for relief. Those living abroad may call (267) 941-1000.
Disaster loss claims: Finally, if you suffer damages due to a federally declared disaster, you might be able to claim those losses on your taxes. Basically, you may deduct personal property losses that are not covered by insurance or other reimbursements.
You have the option claiming these disaster-related casualty losses on your federal income tax return for either the year in which the event occurred, or the prior year.
In addition, taxpayers have extra time — up to six months after the due date of the taxpayer’s federal income tax return for the disaster year (without regard to any extension of time to file) — to make their tax-year claim election.
My post on considerations in making a major disaster tax claim provides an overview of the disaster loss claim process. IRS Publication 547 has more details, as does IRS Form 4684, Casualties and Thefts and its instructions. And, of course, you can talk with your tax adviser about your disaster loss tax options.
Getting advice from a tax professional is a particularly good idea when time-shifted filing could make choosing which year in which to make the loss claim more complicated and confusing.
You also might find these items of interest: