

Photo by Ahsanjaya
Have you been putting off filing your return because you’re having trouble coming up with the money to cover your tax bill?
You might want to check out the Internal Revenue Service’s extended payment options.
File, even if you can’t pay: First things first. Even if you can’t pay all or even any of what you owe, file a tax return.
That will at least prevent the penalty for not-filing.
Yes, the nonfiling penalty is a separate one from the nonpayment penalty. And the assessments for not sending in a return are actually are stiffer than those for not paying the bill that’s shown on your Form 1040.
The failure-to-file penalty typically is 5 percent of the tax owed. It’s assessed each month (or part thereof) that your return is overdue, and maxes out at 25 percent of the unpaid tax bill.
The fail-to-pay penalty is one-half of one percent (0.5 percent) for each month, or part of a month, again up to a maximum of 25 percent of the amount of tax that remains unpaid.
And don’t forget about the interest. The current interest rate is 7 percent per year, compounded daily. The interest rates are adjusted quarterly. Given the inflation expected if the Trump administration’s tariffs continue, that rate could increase.
Pay any amount possible: If you can’t pay your full tax bill, the IRS is happy to take a partial payment.
It’s not the optimal solution, but it can reduce the total amount you’ll owe. Penalty and interest charges will still accrue on the remaining balance, but at least it’s a smaller amount.
So paying something will at least reduce the overall penalty and interest charges that add to your ultimate tax bill.
Extension to file, not to pay: And no, filing an extension won’t get you more time to pay.
Form 4868’s full title specifically notes that it is for an extension to file your return. The form, shown below, and its instructions are clearer.
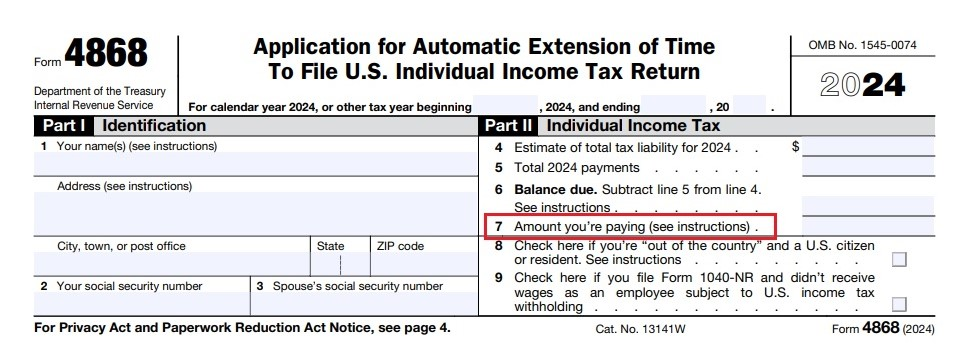
See more tax forms and more about them at Tax Forms 2024 and Tax Forms 2025.
…
You must pay what you owe according to Form 4868 line 7 (highlighted above), or as much as you can, when your file the extension form by April 15.
Online payment plan options: Okay, you can’t cover your federal tax bill in full on April 15. Then it’s time to look at payment options.
Most individual taxpayers qualify for one of the IRS-offered payment plans. The quickest and easiest way to set up such an arrangement is through IRS.gov’s online payment agreement page.
If you’re just a bit short of cash now, but expect to have the money needed to pay your tax bill soon, consider a short-term payment plan. This arrangement, available only to individual taxpayers, is an option when the total balance owed is less than $100,000 in combined tax, penalties, and interest.
Under this short-term payment plan, you have up to 180 days to pay your full tax bill.
The table below has more details (and links to additional IRS information) on the short-term payment plan and potential setup costs.
|
Short-term |
Costs |
|
After applying for a short-term payment plan, payment options include:
|
|
If you need longer, the IRS has, you got it, a long-term payment plan, also known as an installment agreement. The tax agency notes that new, simple payment plan criteria make it easier and more accessible to enter a long-term payment plan when the total balance owed is less than $50,000 in combined tax, penalties and interest.
Taxpayers may pay in monthly payments for up to the collection statute, usually 10 years.
Payments may be set up using direct debit (automatic bank withdrawal), which eliminates the need to send in a payment each month, saves postage costs and reduces the chance of default. Taxpayers should remember that extending the time to pay will increase the applicable interest, penalties, and fees.
Once the online application is complete, the taxpayer is notified immediately whether their plan is approved. There’s no paperwork and no need to call, write or visit the IRS.
The table below has more details (and links to additional IRS information) on the long-term payment plan and potential setup costs.
|
Long-term |
Costs |
|
Option 1: Pay through Direct Debit (automatic monthly payments from your checking account), also known as a Direct Debit Installment Agreement (DDIA). |
|
|
Option 2: After applying for a long-term payment plan, payment options include:
|
|
Again, regardless of which payment pal you choose, do so by April 15. That’s the only way to prevent penalty and interest charges from being imposed.
You also might find these items of interest:
- Ways to electronically pay your tax bill
- Adjusting paycheck withholding can prevent tax-due troubles
- File Form 4868 for an extension if you can’t finish your taxes by April 15
Advertisements
🌟 Search Amazon Tax Products 🌟
The text link above is an affiliate ad. If you click through and then buy a product, I receive a commission.

