

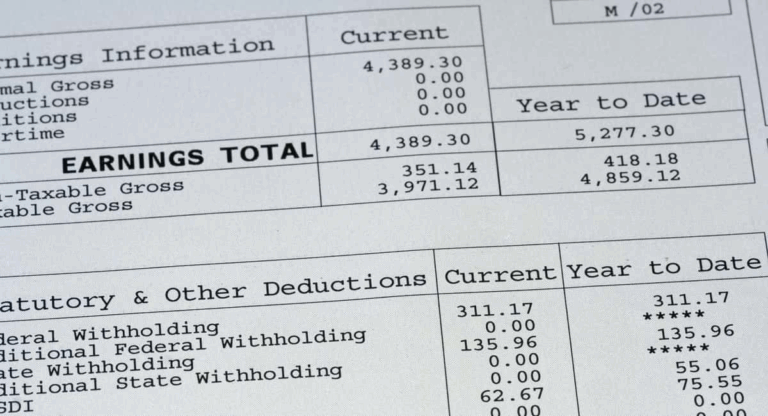
Long-time readers of the ol’ blog know I’m a big fan of Goldilocks paycheck tax withholding. That’s when you get the amount of taxes taken from your pay just right or, since we’re talking taxes, as close as possible to your eventual annual tax liability.
A lot of factors come into play in determining correct withholding. One of them is tax law changes.
The Internal Revenue Service today announced that it has finally updated its online Tax Withholding Estimator to reflect changes to credits and deductions under the One Big Beautiful Bill Act that became law last July 4.
The modifications include the OBBBA’s tax changes on some tip and overtime income, as well as deductions for certain car loan interest amounts and the Senior Bonus tax break for filers age 65 or older.
The IRS says the new withholding tool also more accurately accounts for OBBBA modifications tied to family-related credits, home ownership, and charitable giving.
Using the calculator: If you read some my earlier posts (thanks!) urging you to adjust your withholding and took action, you might want to take another look at the amount you came up with then.
As you know from already taking advantage of the tax withholding estimator, it’s not that hard to use.
And there is no limit on how many times you can change your withholding, aside from your payroll administrator’s patience in dealing with your additional revisions.
If you haven’t yet used the withholding estimator, here’s a quick primer.
The free-to-use Tax Withholding Estimator is available 24/7. It does not require taxpayers to log in or provide personally identifiable information, such as a Social Security number or address.
The estimator takes about 25 minutes to complete. If your tax situation is a relatively simple one, it takes even less time.
The online tool uses a step-by-step guide method where you enter your income, filing status, number of dependents, withholding, credits, and deductions. It takes that information and then provides you a personalized recommendation on whether to adjust withholding.
To get the most accurate results, gather your recent pay statements and a copy of your latest federal income tax return before using the estimator.
If the tool’s analysis suggests withholding changes, either to increase or lower the amount taken each pay period, the estimator will help you complete a new Form W-4, Employee’s Withholding Certificate, or Form W-4P, Withholding Certificate for Periodic Pension or Annuity Payments.
Then give that new withholding document to your employer or pension provider.
Revised estimator can benefit all taxpayers: Even if the OBBBA changes don’t affect you, you still might want to double check your paycheck withholding.
Situations where revising withholding could help include for taxpayers who —
- Hold more than one job or a working spouse.
- Experienced a major life change recently, such as marriage, divorce, the birth or adoption of a child.
- Claim credits, such as the Child and Dependent Care Credit or Adoption Credit.
- Itemize deductions, including mortgage interest or charitable contributions.
- Receive income without automatic tax withheld, such as gig, freelance, or investment income.
- Owed additional tax or received a larger-than-expected refund during their most recent filing season.
You can find more information on the withholding estimator at IRS.gov’s Tax Withholding Estimator FAQs page.
State and other withholding issues: If you live in a state that collects individual income tax, double check your withholding at this level, too.
Depending on where you live, you might also need to complete and give your boss a new state tax withholding form.
Individuals who work in one state, but who legally reside in another state, also should check with their employers — and a tax professional — about what paycheck withholding tax steps they need to take.
Retirees also might want to look into withholding from their Social Security benefits. If you have other income, you could owe tax on some of your federal retirement money.
This could happen if, as a single Social Security recipient, your combined income exceeds $25,000 a year or is more than $32,000 a year if you’re married and file jointly. In this case, you might want to consider having taxes withheld from your monthly federal benefits.
You can tell the Social Security Administration to withhold 7 percent, 10 percent, 12 percent, or 22 percent of your monthly payment to pay the expected tax bill.
Changes eliminate surprises: Whatever your reason for making withholding changes, adjustments can help you avoid surprises at tax time.
When your withholding more closely matches your anticipated tax liability, you won’t face an unexpected tax bill that could lead to potential underpayment penalties.
And for those who over-withholding, adjusting the federal tax taken from your pay will increase the cash you take home each pay period.
You also might find these items of interest:

Paycheck Atlas
The reminder to revisit withholding after a major tax law change is timely. Using a recent pay statement and the prior return should make the estimator much more accurate than relying on a salary headline alone. I also appreciate the note about state withholding for people who live and work in different states, since the federal and state paycheck changes can move in different directions.